
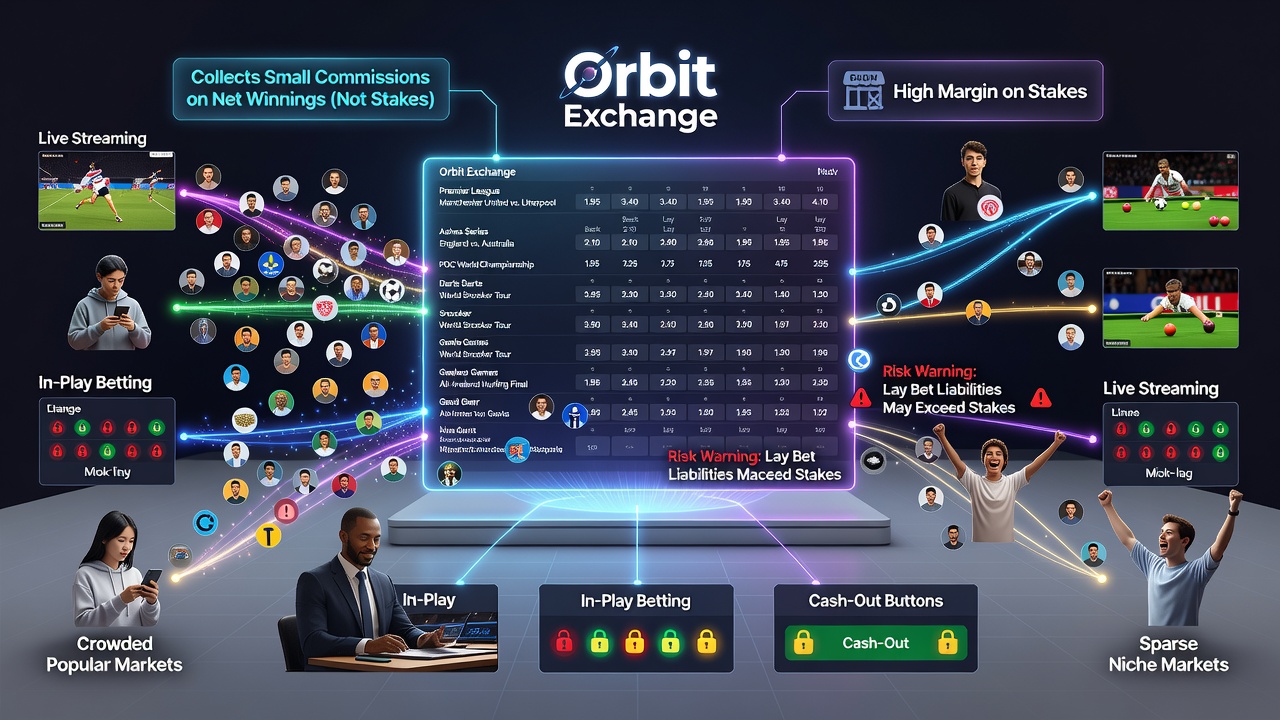
A betting exchange flips the traditional bookmaking model on its head. Instead of wagering against a bookmaker that sets and controls the odds, users on a platform such as Orbit Exchange bet directly against one another, with the operator stepping back into the role of intermediary. That structural difference changes how odds form, how risk is distributed, and who ultimately profits from a winning bet.
Back and Lay: The Mechanics of an Exchange
On a conventional sportsbook, a bettor can only back an outcome. On an exchange, users can also "lay" a bet - effectively taking the bookmaker's side by offering odds for others to back. A back bet wins if the selection occurs; a lay bet wins if it does not. This dual function means any user can act as either bettor or bookmaker on the same market, provided another participant is willing to take the opposing position. The platform's role is limited to matching these opposing views and collecting a commission, typically a small percentage, on net winnings rather than on the stake itself.
This commission-based model, common across exchanges rather than unique to any single operator, means the platform has no direct financial interest in which outcome wins. Its revenue depends on trading volume and liquidity rather than on the house beating individual customers - a distinction that marketing materials often emphasize, though it does not eliminate the underlying uncertainty of betting itself.
Market Range and Product Features
Exchanges tend to cover a broad spread of sports and niche markets, from major football leagues and cricket to less heavily traded events such as darts, snooker, or Gaelic games. Features like in-play betting, cash-out, and live streaming have become standard expectations among active users, largely because they give bettors more control over timing and exposure. Cash-out in particular allows a position to be closed before an event concludes, locking in a result based on current odds rather than waiting for the final outcome - useful for managing risk, though the cash-out value is calculated by the platform and will not always match what a user might expect from the eventual result.
Liquidity as a Structural Limitation
The exchange model depends entirely on having enough opposing bettors in a market. Popular events with high trading volume tend to offer tighter odds and easier matching; niche sports or obscure markets can suffer from thin liquidity, meaning bets may go partially matched or not at all. This is a structural feature of exchanges generally, not a flaw specific to one operator, and it is worth understanding before relying on an exchange for less mainstream markets.
Regulatory and Consumer Considerations
Because lay betting effectively allows users to take on bookmaker-style liabilities, the potential financial exposure can exceed the simple stake involved in a back bet. A lay bet that loses requires paying out the full winnings owed to the backer, which can be substantial relative to the original position. Exchanges typically display these liabilities clearly in the bet slip, but users unfamiliar with the model can underestimate the risk.
As with any wagering platform, commission structures, account verification, and responsible-gambling tools are factors worth checking directly with the operator rather than assuming consistency across the industry. Betting exchanges do not offer better long-term odds of winning than other forms of sports betting - they simply redistribute where the margin is taken and who absorbs it. Consumers should treat any exchange, including Orbit Exchange, as a venue for entertainment carrying genuine financial risk, not a mechanism for guaranteed returns.